Fortune International Group and KAR Properties closed an $817 million construction loan on Wednesday, Oct. 28, for Faena Residences Miami, a financing deal reported as the largest construction loan in Florida history.
Tyko Capital provided the loan, which Walker & Dunlop arranged, according to Commercial Observer. The project’s developers are Fortune International Group, led by Edgardo Defortuna, and KAR Properties, led by Shahab Karmely.
The record-setting financing will support a major new residential development on a prominent stretch of the Miami River, where construction is expected to begin in November.
Two towers planned for the Miami River
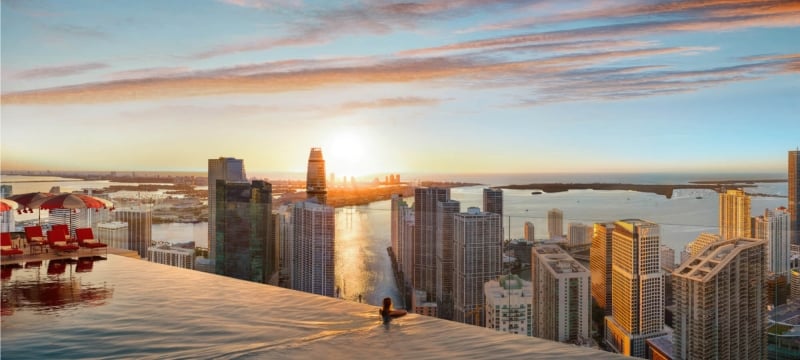
Faena Residences Miami is planned for 24 SW Fourth Street, across the river from Brickell City Centre. The project comprises two towers designed by Rafael Viñoly Architects, with 434 residences in total, according to Commercial Observer.
The Miami River location puts the development at the intersection of a growing residential district and Miami’s downtown core. The project will add a large-scale condominium address to a waterfront corridor that has attracted renewed developer and lender attention.
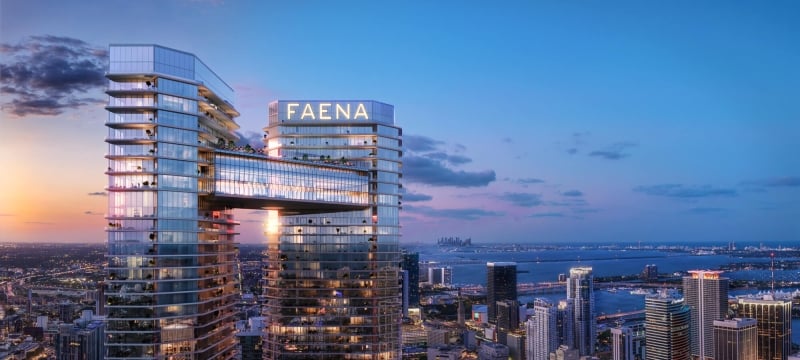
The project carries the Faena name, associated in Miami with the brand’s established presence in Miami Beach. Faena describes the riverfront development as its first standalone residential project in the area. Its official project page features renderings and design information.
$817 million loan and more than $500 million in sales
The $817 million loan is backed by more than $500 million in reported sales to date, the developers told Commercial Observer. Construction is expected to start in November 2026, with completion planned for 2030.
Those figures outline the scale of the financing, but they are not interchangeable measures. The loan is construction debt for a two-tower development, while the sales figure reflects reported presales. Commercial Observer noted that the loan’s terms were not disclosed.
A simple division of the loan amount by the 434 planned residences comes to about $1.88 million in construction debt per residence. That is a scale comparison, not a unit-level allocation. The financing covers construction of the overall project, including towers, amenities and shared spaces, rather than only the residences.
The loan is also about 1.6 times the reported $500 million-plus presales figure. That ratio highlights that the debt exceeds the presale base disclosed to date. It should not be read as a direct measure of risk or loan coverage: presales are not necessarily cash collected, and project financing is tied to construction costs and the development as a whole.
A major vote of confidence in branded waterfront housing
The Faena loan is part of a broader run of large South Florida construction financings. Earlier this month, Driftwood Capital closed $145 million for Riverside Wharf on the same river, while Terra secured $507 million for a Miami Beach tower before presales opened. Together with the Faena financing, the deals point to substantial lender activity around large, branded waterfront developments.
The scale of the loan is notable in a market where financing appetite can vary sharply by project and sales progress. Commercial Observer reported the Faena loan surpasses the previous Florida construction-loan record: a $772 million financing for two West Palm Beach office buildings.
For Miami, the next milestones are tangible: construction getting underway this November and a multi-year build toward the planned 2030 completion. The loan brings a landmark riverfront project closer to that schedule, and signals lender confidence in the appeal of branded condominium development, supported by substantial reported presales.
For more local market context, read our coverage of how South Florida real estate has split into two markets.